Benjamin Fernandes: How Tanzanian Founder NALA Approached the Cost of Sending Money Home
Benjamin Fernandes founded NALA to address cross-border payment difficulties. The Tanzanian entrepreneur's journey highlights compliance, exchange rates, payment rails and the importance of reliable recipient experience.
Source-attributed biographical feature prepared with AI assistance. No first-hand interview, independent performance audit or direct quotes invented. Image rights are not cleared and human editorial verification has not been performed. Remains unpublished pending genuine editorial approval.
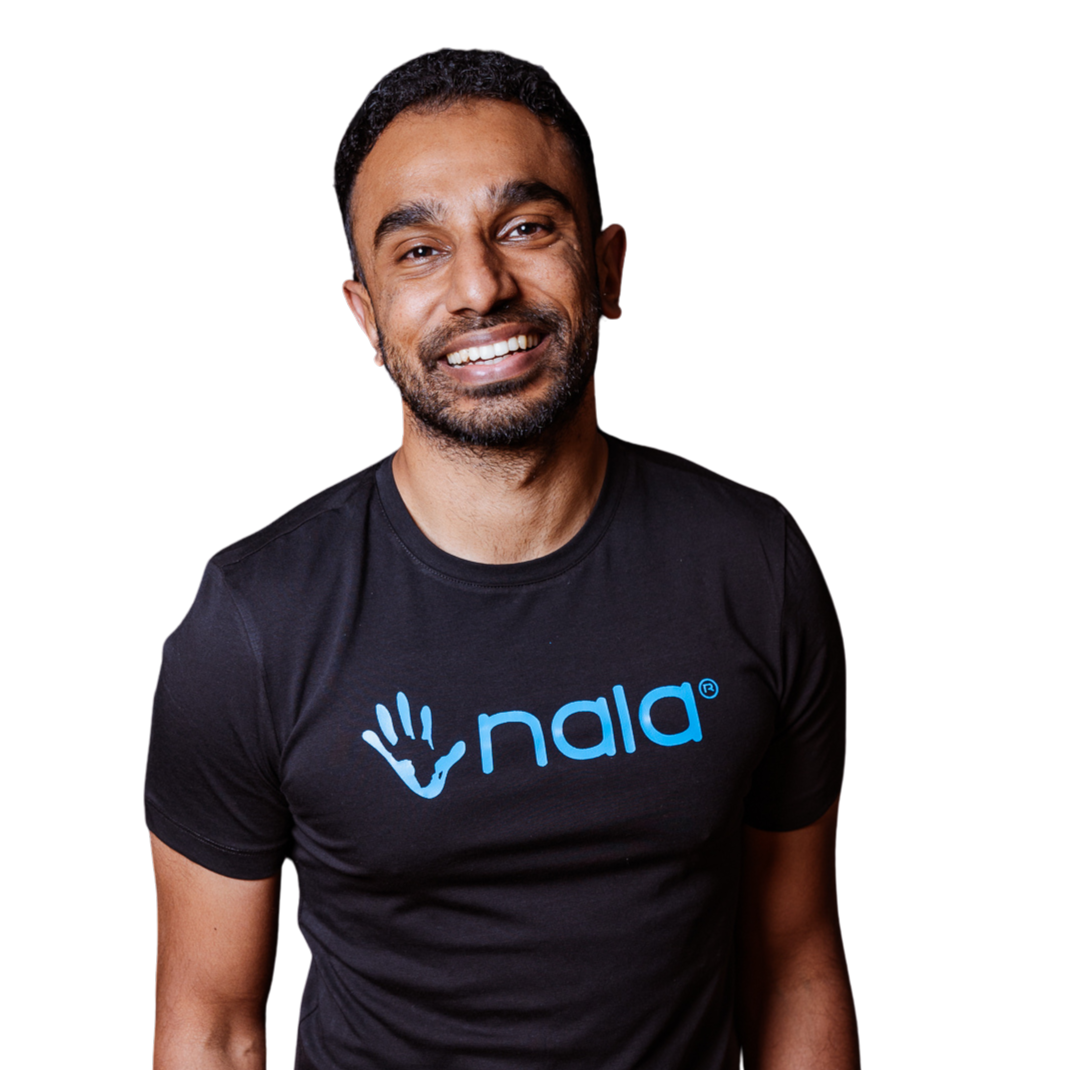
Entrepreneur: Benjamin Fernandes Country: Tanzania Sector: Cross-border payments and fintech Venture(s): NALA
Why this entrepreneur matters
Benjamin Fernandes founded NALA to address cross-border payment difficulties. The Tanzanian entrepreneur's journey highlights compliance, exchange rates, payment rails and the importance of reliable recipient experience.
Background and entrepreneurial journey
Benjamin Fernandes is a Tanzanian entrepreneur and founder and CEO of NALA. The company's leadership page explains that he previously worked on mobile payment services for television subscriptions in East Africa. NALA developed international money-transfer services and has subsequently built broader cross-border payment capabilities. Y Combinator lists Fernandes as an active founder.
The problem behind the venture
Families and businesses can face costs that are not captured by one advertised transfer fee: exchange-rate margins, payment-method restrictions, recipient charges, delays and support problems. A remittance product must reliably move money through regulated partners in more than one country, under different banking and consumer-protection systems.
Business model and execution
NALA's customer proposition involves helping people transfer value across borders. The operational challenge is coordinating supported sender accounts and destination payment rails, safeguarding funds as required and reconciling transactions when one part of the chain fails. A cross-border company may be growing even when it is not eligible to serve every country or customer category.
Practical lessons for aspiring founders
A founder considering a payments startup should begin with one lawful transaction corridor. Map every intermediary, regulatory permission, fee and possible failure. Test delayed and reversed payments before promising instant service. Be transparent about the final amount recipients receive. Entrepreneurs who do not have regulated payment infrastructure can still create useful services around invoices, reconciliation or customer education without holding client funds.
What ITBank will be watching
Reliable payouts, transparent total transfer costs and access to efficient payment systems for smaller African businesses and families.
Limits of this profile
The company and media have reported fundraising rounds and credit financing; a facility's maximum value is not automatically cash received or company revenue. ITBank has not tested live transactions, present fees or licensing in all countries.
Editorial note: Independent desk-researched ITBank profile prepared on 28 October 2026, with AI assistance and identified sources. It is not an interview, first-hand field investigation, sponsorship, verified financial audit or investment recommendation. Biographical and venture descriptions are based on the sources linked below.
Sources
Report a factual issue · Advertising & affiliate policy
 Intron Startup Profile: Building Voice Technology Around African Speech ↗
 BuuPass Startup Profile: Why Digital Bus Tickets Need Reliable Operator Systems ↗